The VC landscape in LatAm so far in 2026 has a clear winner: its name is Mexico
The last 12 months are marking a before-and-after moment for Latin American venture capital. For the first time, the region has seen multiple rounds that, five years ago, would have seemed straight out of Silicon Valley. According to data from Cuantico VP, the top 10 mega-deals are dominated by fintech and software, and almost the entire game is being played between Mexico and Brazil, with Argentina entering as a special guest.
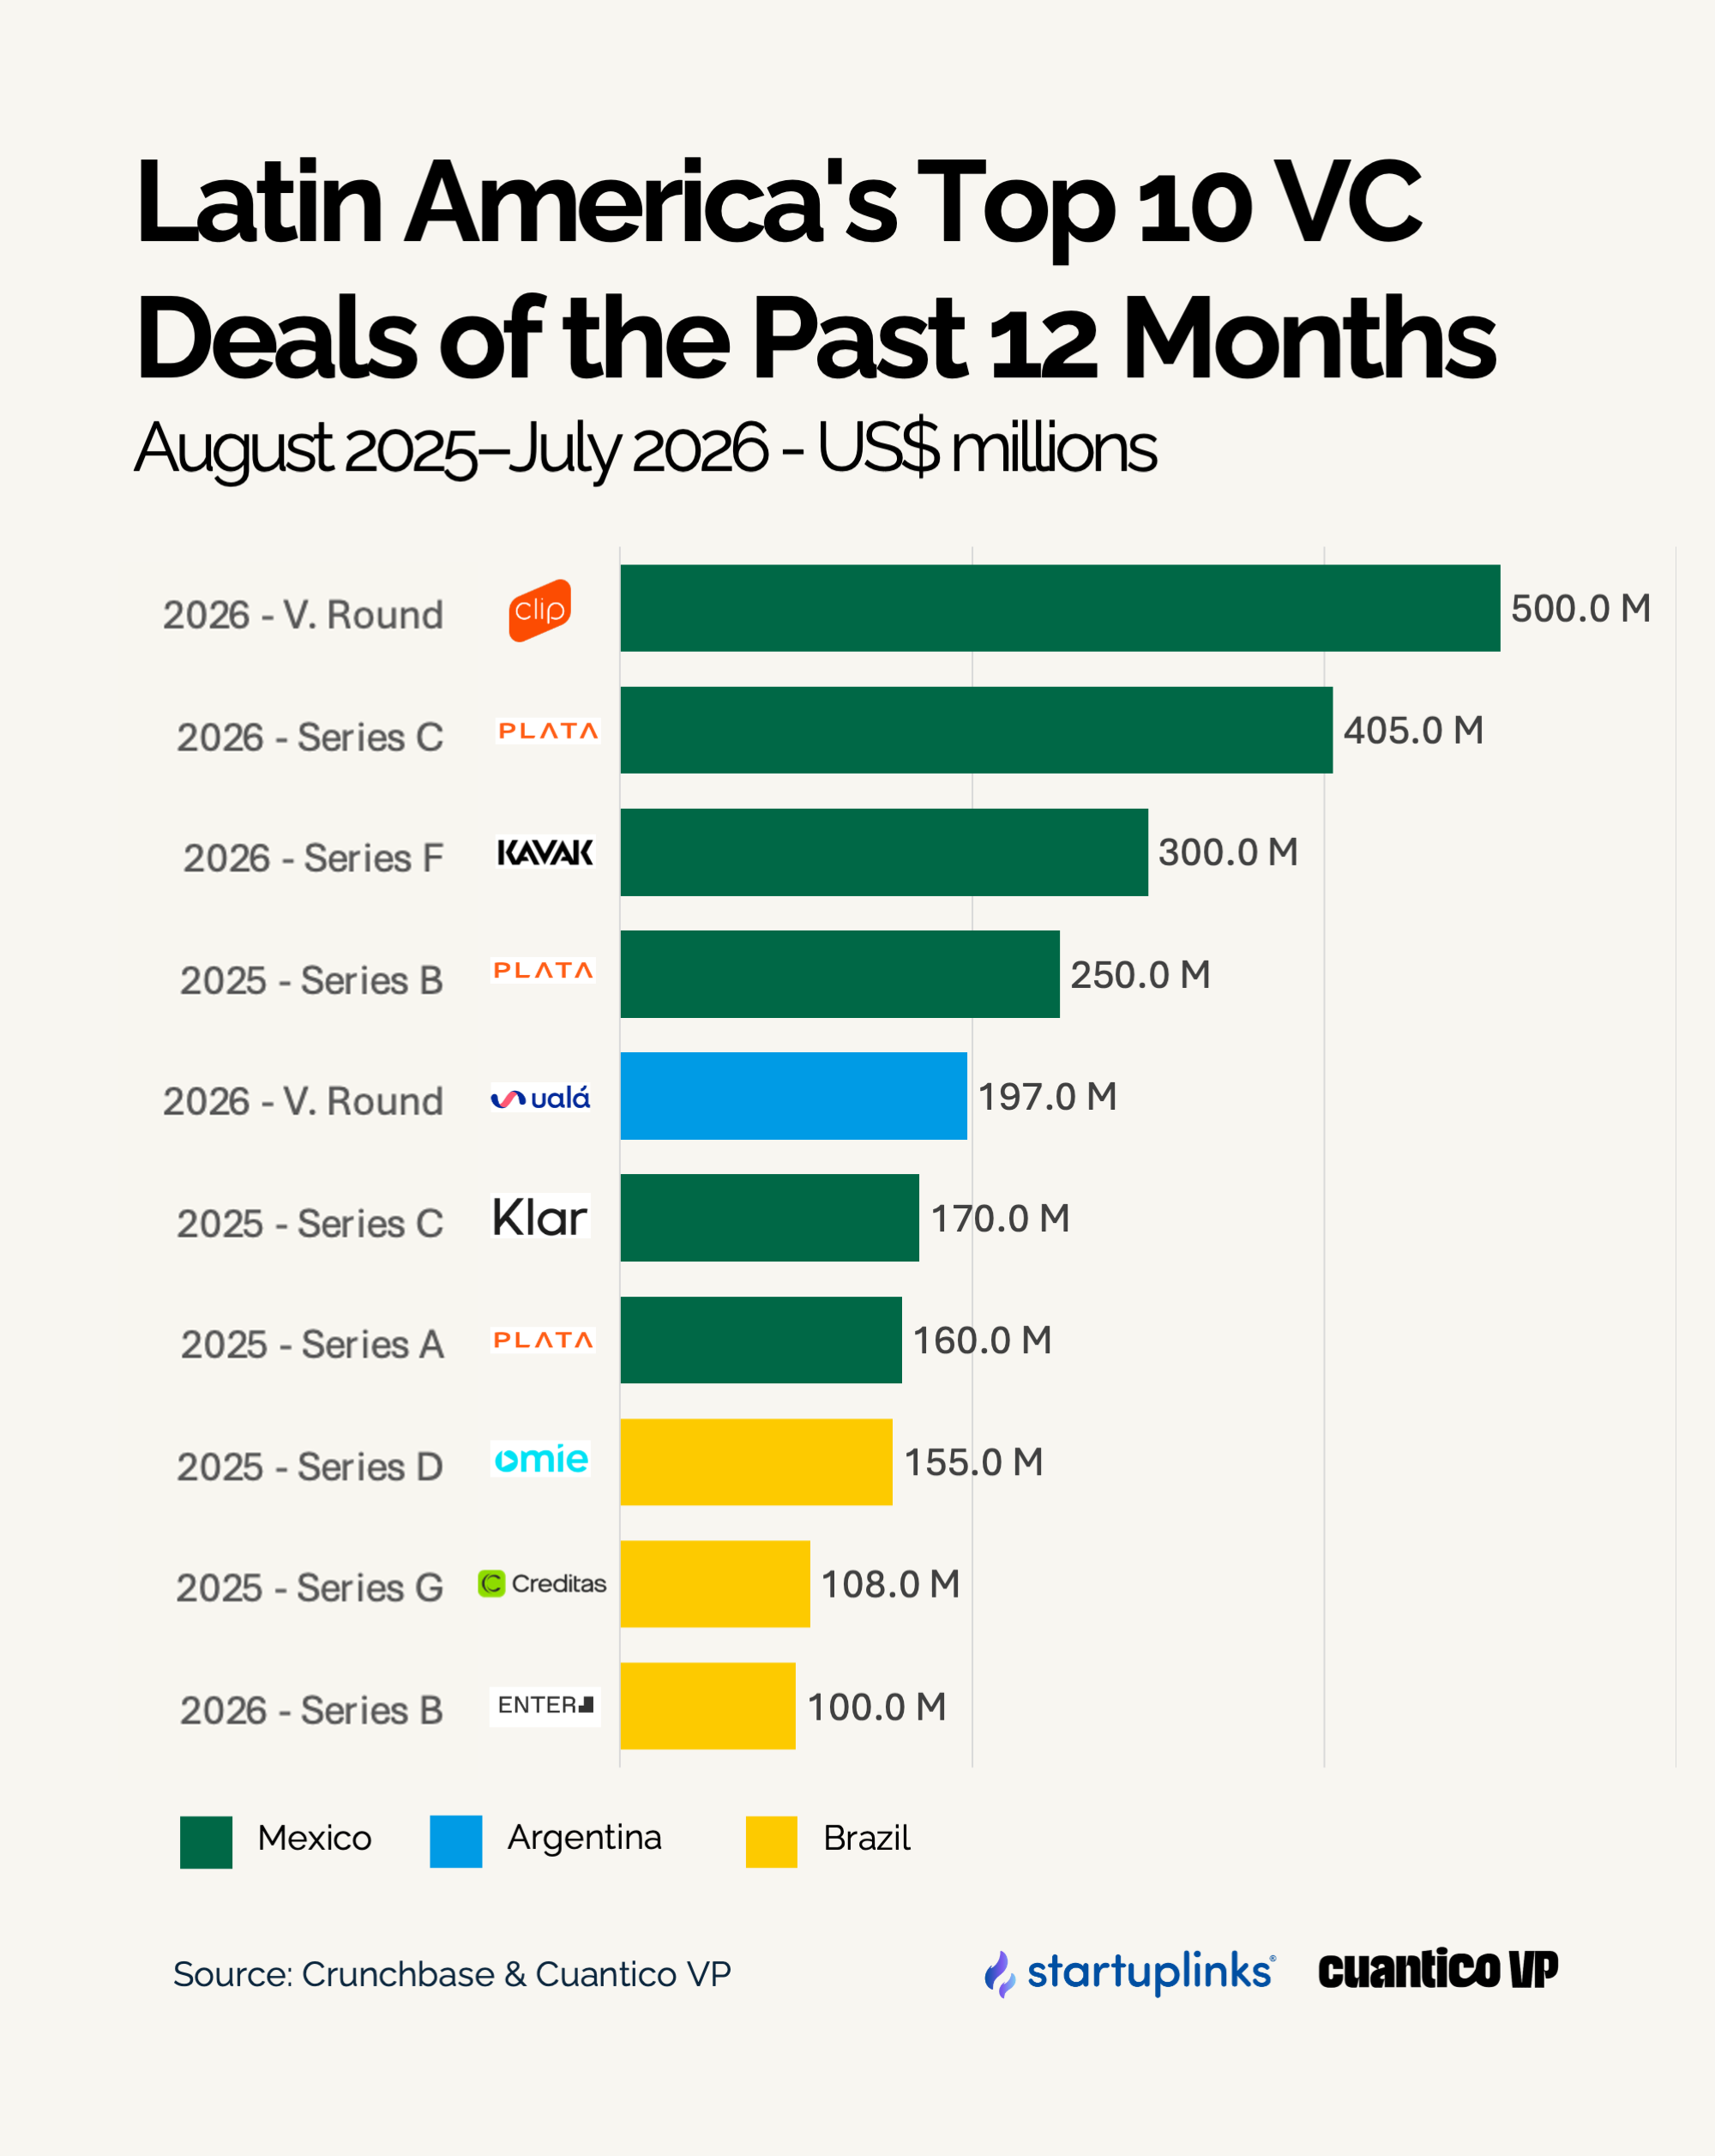
The top 10, check by check
The table shows a very clear ranking by amount:
- Clip – Venture Round 2026 – US$500M (Mexico): the undisputed leader of the list. A round that consolidates Clip as one of the major payment enablers in the region and pushes up the ceiling of what a Mexican fintech can raise at the late stage.
- Plata – Series C 2026 – US$405M (Mexico): a Series C worth more than US$400 million in credit and rewards, coming just a few months after Plata closed its Series B. It positions the company as one of the most aggressive growth stories in Mexican fintech.
- Kavak – Series F 2026 – US$300M (Mexico): the classic venture case in used cars continues to raise capital at global scale, now in its Series F, confirming that “regional champions” have not disappeared from growth funds’ radar.
- Plata – Series B 2025 – US$250M (Mexico): the prelude to the mega Series C. This Series B on its own would already be a massive deal for the region; in hindsight, it looks like the first step in a capital escalation with almost no local precedent.
- Ualá – Venture Round 2026 – US$197M (Argentina): the only round in the top 10 outside Mexico and Brazil. Ualá is consolidating its position as the reference digital bank in the Southern Cone and shows that Argentina can still produce deals at a continental scale.
- Klar – Series C 2025 – US$170M (Mexico): more Mexican fintech, this time in credit and cards for consumers. This US$170M Series C reinforces the narrative that the “new retail banking” in Mexico is being played among a handful of very well-funded players.
- Plata – Series A 2025 – US$160M (Mexico): Plata’s third step on the table. A US$160M Series A would, by itself, be an outlier; here it appears as the beginning of an A–B–C sequence that is redefining capital scales in early and growth stages.
- Omie – Series D 2025 – US$155M (Brazil): the first Brazilian representative in the ranking. Enterprise software (ERP/CRM) for SMEs, showing that B2B SaaS can also generate nine-figure checks in LatAm.
- Creditas – Series G 2025 – US$108M (Brazil): secured lending and consumer credit, with a Series G that confirms Cuantico VP’s findings: credit-focused fintech remains one of the main magnets for large funds.
- Enter – Series B 2026 – US$100M (Brazil): an AI-powered legaltech that, with US$100M in its Series B, is approaching the major leagues even before reaching the classic growth stage. It is a sign that AI applied to specific verticals is also capturing large checks.
The key block: the Mexico–Brazil duopoly
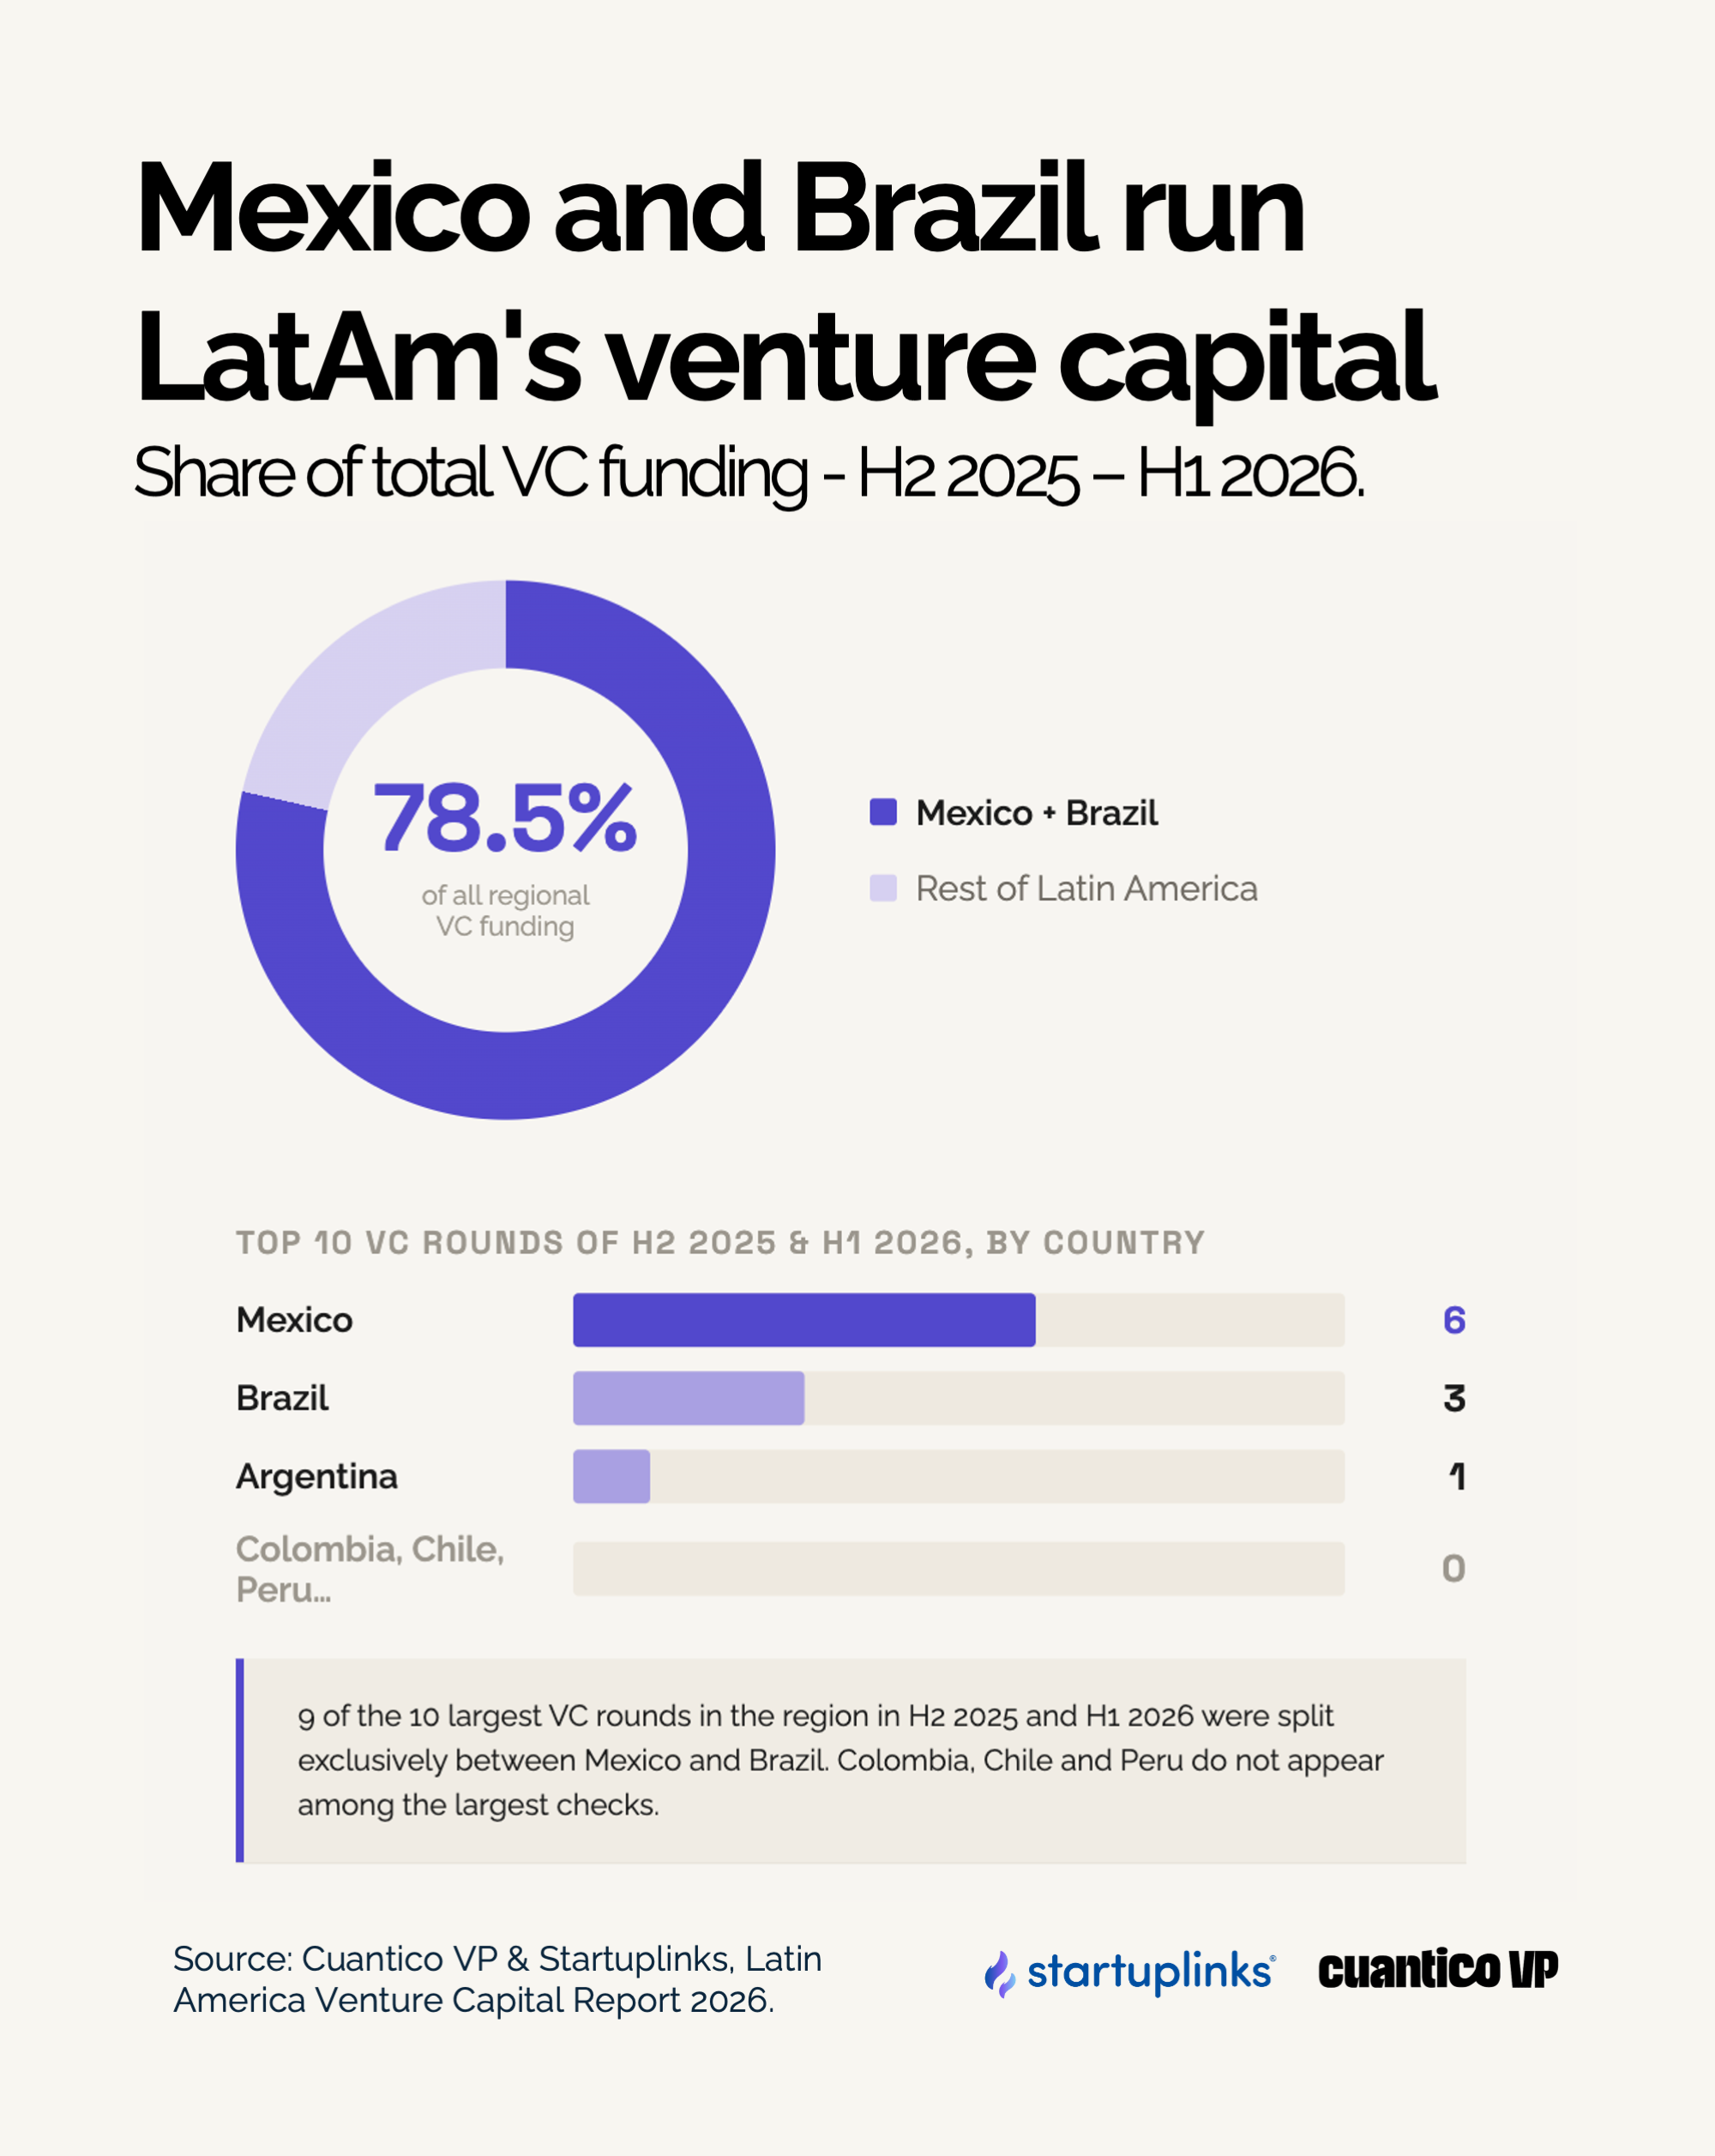
Looking at the geographical distribution of countries in the region, the message is blunt:
- Mexico places 6 of the 10 rounds in the ranking: Clip, the three Plata rounds, Klar, and Kavak, all above US$150M.
- Brazil appears with 3 rounds: Omie, Creditas, and Enter.
- Argentina enters with 1 round: Ualá, the only exception to the duopoly.
In other words, 9 of the 10 largest VC rounds of the last twelve months were played exclusively between Mexico and Brazil. The rest of the region—including very active ecosystems such as Colombia, Chile, or Peru—simply does not show up in the picture when it comes to the largest checks.
This connects with Cuantico VP’s broader diagnosis: Brazil and Mexico already concentrated 78.5% of all regional venture capital in 2025, and this top 10 only puts names and logos to that statistic. The ranking works almost as a power map: wherever these deals are happening, the next generation of “regional champions” is being built; wherever they are not, ecosystems are forced to compete for medium or small rounds.
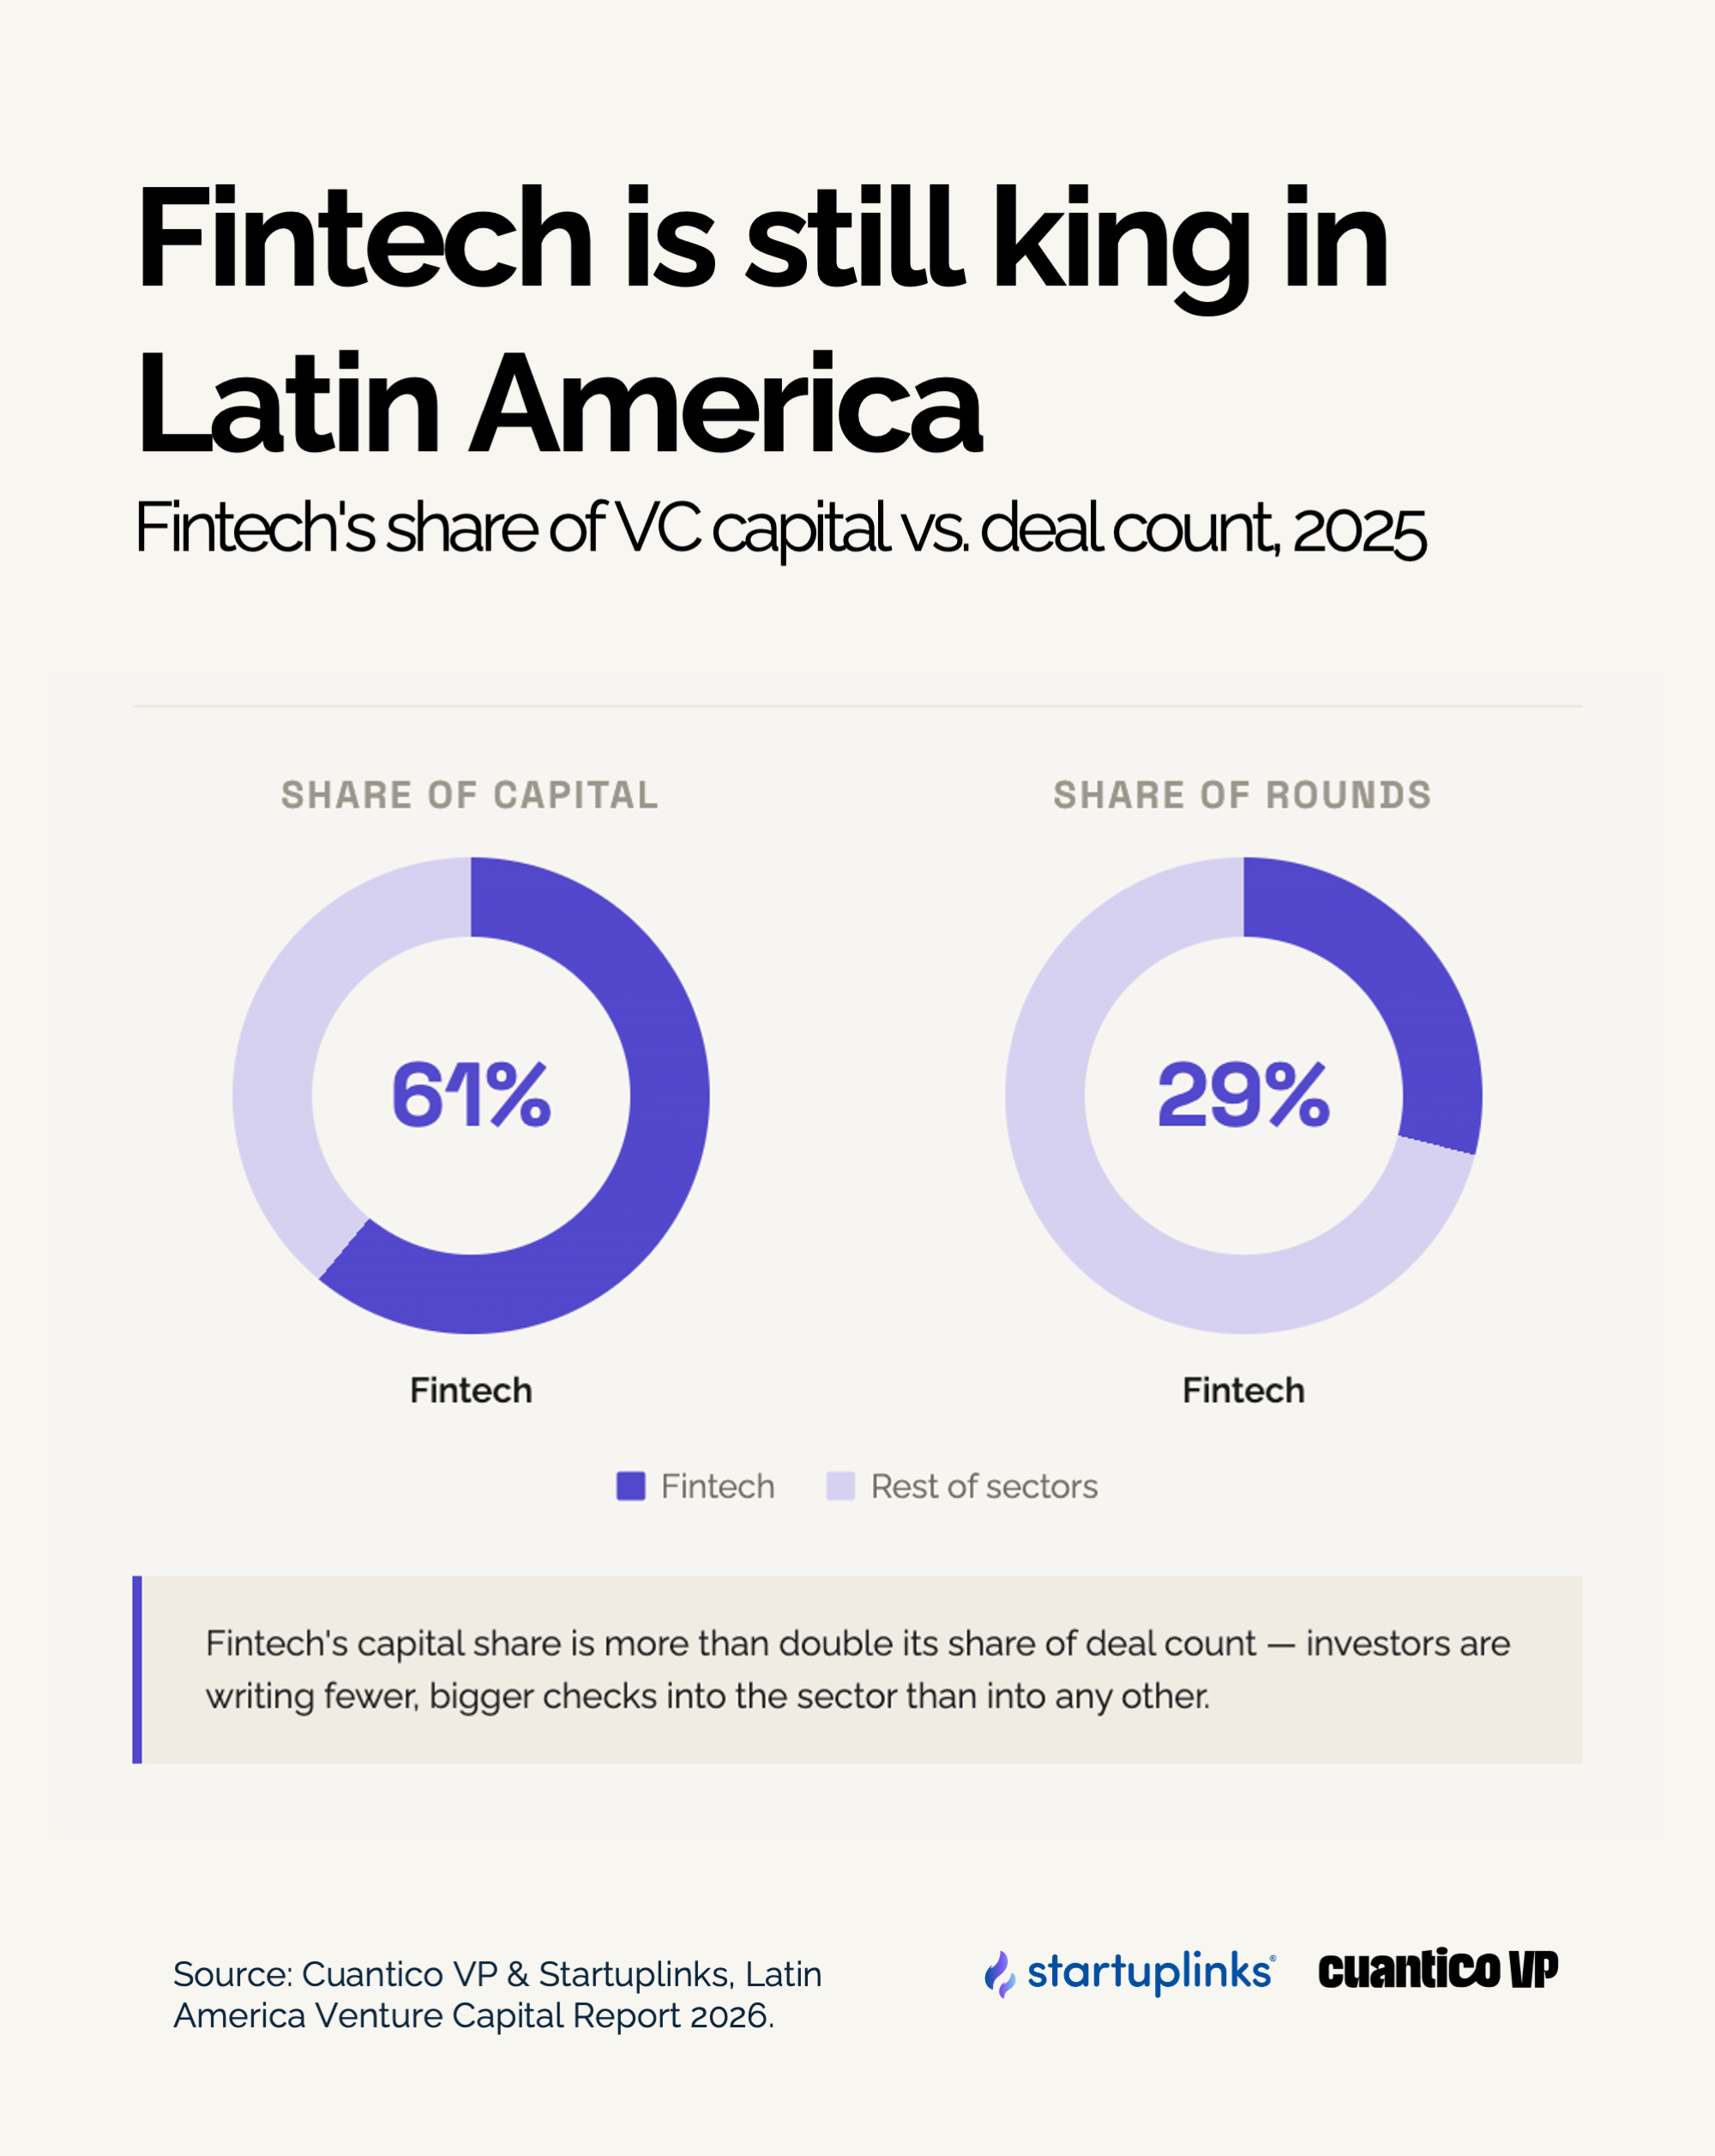
Fintech is still king (and now occupies almost the entire board)
The list reinforces another central idea published in Cuantico VP’s reports: fintech captures 61% of regional capital with just 29% of the rounds. In the top 10, this translates into:
- Payments (Clip), cards and consumer credit (Plata, Klar, Ualá), secured lending (Creditas), and BNPL/digital commerce.
- Only three companies outside pure fintech—Kavak (autos), Omie (ERP/CRM), and Enter (AI legaltech)—manage to break into the list, and even they have a strong financial or software infrastructure component.
In practice, this means that the biggest checks in LatAm are still being written in financial services and associated software. Whoever builds the rails for money, credit, or bankable payments plays in a funding league that other sectors have yet to reach.
Dangerous anchor or sign of maturation?
Jose Kont, Partner at Cuantico VP, warns about a very clear “anchor effect”: “These record rounds are starting to be used as benchmarks in fundraising meetings, pitch decks, and valuation negotiations. When founders cite a US$100M Series A or a US$200M Series B, the risk is that they try to replicate the price without replicating the traction.”
The snapshot this top 10 leaves behind is both clear and unsettling: LatAm is learning how to play in the league of mega-checks, but it is doing so on uneven ground. Fintechs based in Mexico and Brazil are generating mega-rounds and regional champions; founders and companies coming from other ecosystems risk getting stuck in second gear, watching these transactions from the sidelines.